

<2026> Global LIB Production Line Expansion Outlook (~2035)
Only 74% of Announced Plans Become Effective Supply
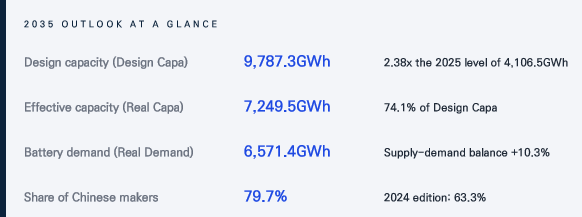
Global lithium-ion battery design capacity (Design Capa) is forecast to reach 9,787.3GWh in 2035, 2.38 times the 2025 level of 4,106.5GWh. Most of the growth comes early: 5,012GWh is added in 2026-2030, against just 669GWh in 2031-2035. The 2026-2030 additions represent roughly USD 305.7 billion of investment (estimate).
Not every announced plan will be built. After adjusting for the likelihood of construction at each project stage, applying an 85% utilization rate and excluding IT-only lines, effective capacity (Real Capa) comes to 7,249.5GWh in 2035, or 74.1% of design capacity. With 34.6% of all plans (3,382GWh) not yet operating, how quickly projects break ground and start up will shape the supply outlook.
Measured against Real Demand, the supply-demand balance narrows from +67.1% in 2026 to +10.3% in 2035: capacity additions bunch up before 2030, while demand keeps growing after that. The surplus is largest in 2026-2028, and low utilization during these years could delay new construction.
The regional picture is more uneven. With expansion concentrated in plants in China, 2035 self-sufficiency reaches 194.6% in China but only 63.5% in North America and 38.1% in Europe. By maker nationality, the Chinese share rises to 79.7% from 63.3% in the 2024 edition. Korean plans fell by 550.8GWh as companies cut capacity to announced levels, and European plans by 681.9GWh after the Northvolt bankruptcy and project cancellations.
Policy has shifted as well. The US has ended EV purchase tax credits and kept only the production credit (45X); Europe is moving to ease its 2035 target while tightening local production requirements; China combines capacity regulation with export controls on technology and products. Because all three regions now tie support to where batteries are made, policy changes are more likely to delay start-up than to cancel plans.
This report compiles the expansion plans of 555 lines and 109 companies at line level, forecasts capacity through 2035 by company, nationality, plant location, form factor and cathode, and examines the supply-demand balance, policy and risks. We hope it proves useful for business planning and investment decisions across the battery industry.
| 0. Executive Summary | ||
| 0.1 | Key Findings | 7 |
| 0.2 | Key Changes from the 2024 Edition | 8 |
| I. Market and Demand Basis | 9 | |
| 1.1 | Vehicle and EV Sales Outlook | 10 |
| 1.2 | Battery Demand Outlook | 11 |
| 1.3 | Regional Demand Divergence | 12 |
| 1.4 | Demand Composition | 13 |
| II. Global Expansion Overview | 14 | |
| 2.1 | Overview | 15 |
| 2.1.1 | Global LIB Capacity | 15 |
| 2.1.2 | Changes from the 2024 Edition | 16 |
| 2.2 | Companies | 17 |
| 2.2.1 | Ranking by Company | 17 |
| 2.2.2 | Supplier-OEM Links | 18 |
| 2.3 | Regions | 20 |
| 2.3.1 | Scale by Region | 20 |
| 2.3.2 | Expansion Outlook by Country | 21 |
| 2.3.3 | Capacity outside China | 22 |
| 2.3.4 | Nationality Mix by Region | 23 |
| 2.3.5 | Top 5 Makers by Region | 24 |
| 2.4 | Products and Technology | 25 |
| 2.4.1 | Expansion by Form Factor | 25 |
| 2.4.2 | Form Factor by Region | 26 |
| 2.4.3 | Expansion by Cathode | 27 |
| 2.4.4 | Cathode by Region | 28 |
| 2.4.5 | Application by Region | 29 |
| 2.4.6 | Technology Shifts | 30 |
| 2.5 | Investment Conversion of New Capacity | 32 |
| III. Expansion Outlook by Company | 33 | |
| 3.1 | Korean Makers | 34 |
| 3.1.1 | LGES | 34 |
| 3.1.2 | Samsung SDI | 39 |
| 3.1.3 | SK On | 44 |
| 3.1.4 | Korea Region Expansion Summary | 48 |
| 3.2 | Chinese Makers | 49 |
| 3.2.1 | CATL | 49 |
| 3.2.2 | BYD | 55 |
| 3.2.3 | EVE Energy | 60 |
| 3.2.4 | CALB | 65 |
| 3.2.5 | Chuneng New Energy | 69 |
| 3.2.6 | Sunwoda | 71 |
| 3.2.7 | AESC | 75 |
| 3.2.8 | Gotion | 78 |
| 3.2.9 | SVOLT | 82 |
| 3.2.10 | REPT | 84 |
| 3.2.11 | Farasis | 86 |
| 3.2.12 | Great Power | 88 |
| 3.2.13 | Do-Fluoride | 90 |
| 3.2.14 | Zenergy | 92 |
| 3.2.15 | Hithium | 94 |
| 3.2.16 | Lishen | 96 |
| 3.2.17 | Ganfeng Li Energy | 98 |
| 3.2.18 | BAK | 100 |
| 3.2.19 | Wanxiang 123 | 102 |
| 3.2.20 | SANY Hongxiang | 103 |
| 3.2.21 | Trina Storage | 105 |
| 3.2.22 | 36 Small and Mid-sized Chinese Makers | 107 |
| 3.2.23 | Design Capa by Province · Municipality · Autonomous Region in China | 111 |
| 3.2.24 | Top 21 Makers: Rank Changes | 112 |
| 3.2.25 | China Region Expansion Summary | 113 |
| 3.3 | Japanese Makers | 114 |
| 3.3.1 | Panasonic | 114 |
| 3.3.2 | PPES | 117 |
| 3.3.3 | Toyota Battery | 119 |
| 3.3.4 | TBMNC | 121 |
| 3.3.5 | GS Yuasa | 123 |
| 3.3.6 | Murata | 125 |
| 3.3.7 | 5 Other Japanese Makers | 127 |
| 3.3.8 | Japan Region Expansion Summary | 128 |
| 3.4 | North American Makers | 129 |
| 3.4.1 | Tesla | 129 |
| 3.4.2 | Lyten | 131 |
| 3.4.3 | Ford | 133 |
| 3.4.4 | Amplify Cell Technologies | 135 |
| 3.4.5 | 4 Other North American Makers | 137 |
| 3.4.6 | North America Region Expansion Summary | 138 |
| 3.5 | European Makers | 139 |
| 3.5.1 | PowerCo(VW) | 139 |
| 3.5.2 | Verkor | 142 |
| 3.5.3 | ACC | 144 |
| 3.5.4 | Basquevolt | 146 |
| 3.5.5 | 10 Other European Makers | 148 |
| 3.5.6 | Europe Region Expansion Summary | 149 |
| 3.6 | Seven Asian Makers | 150 |
| 3.7 | Line Details of Small Makers | 151 |
| IV. Mid- to Long-Term Supply-Demand | 152 | |
| 4.1 | Basis for Supply-Demand Assessment | 153 |
| 4.2 | Global Supply-Demand Balance | 154 |
| 4.3 | Regional Supply-Demand Balance | 155 |
| V. Policy and OEM Strategy | 156 | |
| 5.1 | Policy Landscape and Impact on Expansion | 157 |
| 5.2 | Policy by Region | 158 |
| 5.2.1 | North America | 158 |
| 5.2.2 | EU | 160 |
| 5.2.3 | China | 162 |
| 5.2.4 | Korea · Japan | 164 |
| 5.3 | OEM Strategy | 165 |
| 5.3.1 | OEM Battery Insourcing | 165 |
| 5.3.2 | Insourcing Trends by OEM | 166 |
| 5.4 | Chapter 5 Summary | 168 |
| VI. Risks and Conclusions | 169 | |
| 6.1 | Risks | 170 |
| 6.1.1 | Risk Map | 170 |
| 6.1.2 | Oversupply Risk | 171 |
| 6.1.3 | Policy and Technology Risks | 172 |
| 6.1.4 | Risk Exposure by Company and Region | 173 |
| 6.2 | Conclusions and Next Checkpoints | 174 |